Thanks for reading my letter. Here's where to get your copy.
Retiring in the next 5 years?
Playing it safe may be the riskiest move you make.
A free, plain-English book on the mistake I see most often at retirement, and the simple plan I use instead. If it's a fit, I'll mail you a printed copy, along with a free bonus worksheet.
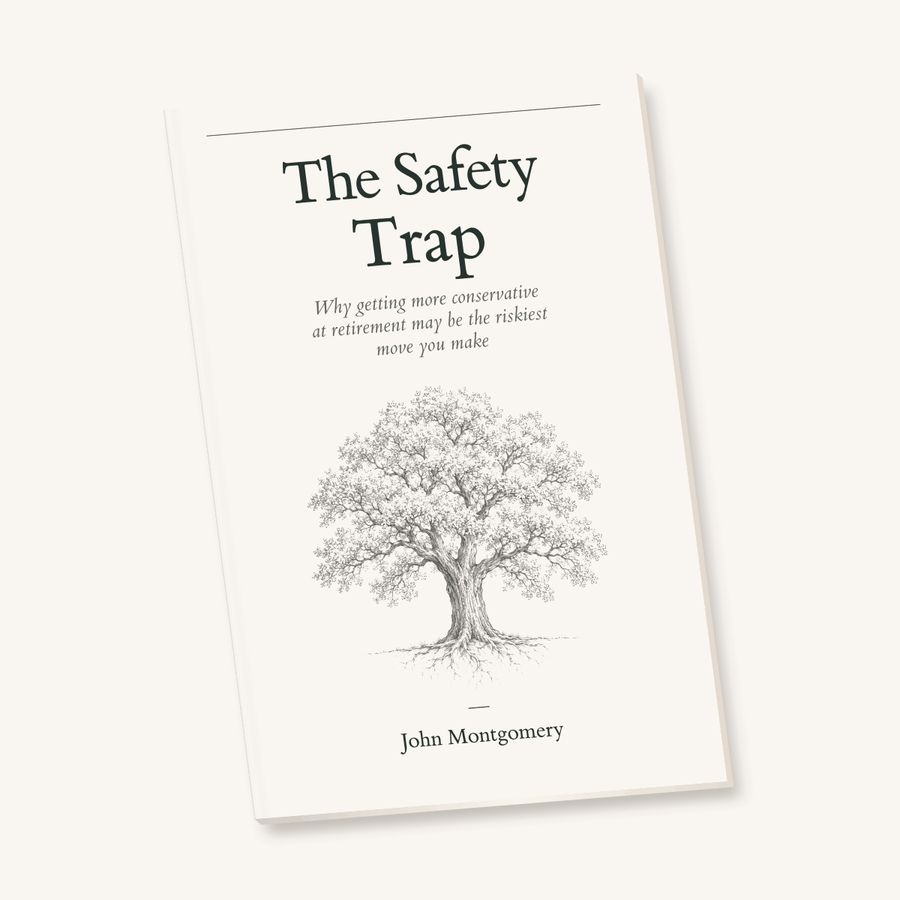
Send me the free book
- The printed book, mailed to you
- The PDF, right away
- Bonus: the Storm Reserve Worksheet, in the envelope with your book
Printed copies are for readers within about 5 years of retirement (or recently retired) with $600,000 or more saved. Everyone gets the PDF.
Dear friend,
The day you retire, you'll hear the same advice from almost everyone. Get more conservative. Move more to bonds. Move more to cash. Lock it all down.
It sounds responsible. It feels safe. And for a lot of people, I think it's the wrong move.
Here's why. For a married couple who are both 65, the odds are roughly even (or better) that at least one of you makes it to 90.1 That's 25 to 30 years of retirement to fund. That's a long time for prices to climb. At 3% a year, what costs $100 today costs about $243 in 30 years.2
A bad year in the market hurts. 30 years of rising prices hurts more. The money can still be there. It just buys less. That's what I call the safety trap.
So I wrote a short book about it. It answers the 3 questions I hear most from people getting close to retirement:
- Do I have enough?
- What if the market crashes right after I retire?
- How do I turn all this into a paycheck?
It's the same thing I'd tell you if you were sitting across the table from me.
Inside the book
Here's some of what you'll discover:
- Why many target-date funds start playing it safe when you still have 20 years of paychecks ahead of you, and what that "safety" quietly costs.
- The difference between volatility and risk. Mixing them up is how good savers talk themselves into bad decisions.
- A simple way to find your number: the yearly income you want, a starting withdrawal rate, and the math in between.
- The 3 mistakes I see all the time, including the Social Security decision people make based on what a neighbor did.
- Where to look for money you forgot you had: the old 401(k) from 2 jobs ago, the 457 plan, the IRA you rolled over in 2009 and haven't opened since.
- What to do if you run the numbers with a year to go and come up short. (There are 3 levers. Most people only think of 1.)
- The Storm Reserve: the 4-step setup I use so you're far less likely to be forced to sell near the bottom of a bad market.
- How to turn savings into a paycheck that's planned to get a raise along the way, with a worked example.
- What you should expect from your advisor the next time markets fall hard.
Free bonus with the printed copy
The Storm Reserve Worksheet
A single fill-in-the-blank page that helps you figure out how much cash to set aside before your retirement income starts, and where it should sit. It's meant to be worked with a pencil, so it only comes on paper, tucked in with your book.
This book isn't for everyone.
It's for you if…
- You plan to retire in the next 5 years, or you just did.
- You've saved a meaningful amount, and you want it to last 30 years.
- You've been told it's time to "get conservative," and something about that bugs you.
- You have accounts scattered all over and no clear picture of the whole thing.
Skip it if…
- You're looking for hot stock tips or a market prediction.
- You want a guarantee that nothing will ever go down. Nobody can give you that honestly.
- Retirement is 20 years away. (Keep it in mind, though.)
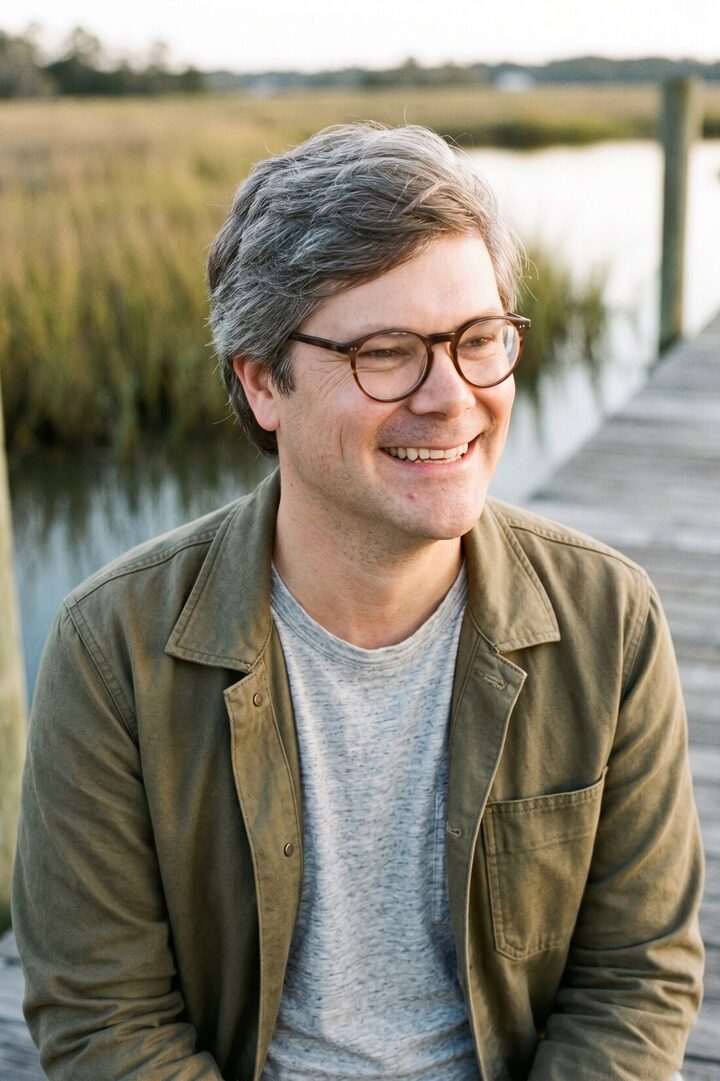
Who wrote it
I'm John Montgomery.
I founded Montgomery Wealth Advisors in 2015. Shreveport has been home since middle school, and I'm married with 3 daughters.
I keep my client list small on purpose. Most of my work is helping people within a few years of retirement turn a lifetime of saving into a retirement that lasts. This book is how I'd explain it if you were sitting across from me.
John Montgomery
Free. Short. Straight answers.
Read it before you make your retirement-day decisions.
It takes about an hour. Those decisions can shape the next 30 years.
Yes, send me the bookP.S. The book is free, and so is the Storm Reserve Worksheet that comes with the printed copy. There's no meeting to book and nothing to buy. Just tell me where to send it.
1 Society of Actuaries and American Academy of Actuaries, Actuaries Longevity Illustrator, longevityillustrator.org. Estimates for a 65-year-old couple put the chance that at least one reaches 90 at roughly 50% to 58%, depending on health and assumptions.
2 Hypothetical illustration of 3% annual inflation compounded for 30 years. The Consumer Price Index (CPI-U) rose about 3.0% a year from 1926 to 2025 (U.S. Bureau of Labor Statistics, via the Federal Reserve Bank of Minneapolis). Future inflation may be higher or lower.